Map the current transaction journey · Core coordination role
Payment-processing professional
Payment Processing
Compare merchant services, point-of-sale support and supported payment features.

SJBA Project Connections / Your Business
Start with the transactions and operational problems you need to handle. Compare payment proposals, reconciliation, staff routines and technical dependencies before changing the system customers use to pay.
Your planning readiness check
Choose a starting point to see relevant professional roles. Optional services remain your choice.
Your next step
List in-person, online, telephone and invoice payments, together with refunds, cancellations and reconciliation.
Read this part of the guideConfirm scope, qualifications, fees and availability directly.
Map the current transaction journey · Core coordination role
Payment Processing
Compare merchant services, point-of-sale support and supported payment features.
Your next step
Have the accounting contact specify the reports and timing needed to connect sales, refunds, fees and deposits.
Read this part of the guideConfirm scope, qualifications, fees and availability directly.
Agree reconciliation and security responsibilities · Optional; based on your needs
Accounting
Define reconciliation and reporting needs across transactions, fees and deposits.

Agree reconciliation and security responsibilities · Optional; based on your needs
Assess technical security responsibilities where the project requires specialist expertise.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Your next step
Check purchase, refund, decline, receipt and reporting scenarios before rollout, following provider-approved testing procedures.
Read this part of the guideConfirm scope, qualifications, fees and availability directly.
Test, hand over and review · Core coordination role
Payment Processing
Compare merchant services, point-of-sale support and supported payment features.
Not every project needs every role. Current member availability is resolved live; unrepresented specialties are identified below.
Stage 2 · Core coordination role
Payment Processing
Compare merchant services, point-of-sale support and supported payment features.
Stage 3 · Optional; based on your needs
Accounting
Define reconciliation and reporting needs across transactions, fees and deposits.
Stage 4 · Optional; based on your needs
Digital Marketing
Coordinate customer-facing messaging and marketing dependencies; technical integration is separately verified.
Stage 4 · Optional; based on your needs
Implement and test the exact integration within confirmed technical scope.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Stage 3 · Optional; based on your needs
Assess technical security responsibilities where the project requires specialist expertise.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Start with the transactions and operational problems you need to handle. Compare payment proposals, reconciliation, staff routines and technical dependencies before changing the system customers use to pay.
List in-person, online, telephone and invoice payments, together with refunds, cancellations and reconciliation. Record where work is duplicated or information is missing. Use business process descriptions without collecting card numbers in the planning document.
Decide which problems must be solved now and which features are optional. A new terminal will not automatically fix unclear refund procedures or accounting responsibilities.
Ask each provider to explain transaction charges, recurring fees, equipment arrangements, contract length, renewal, termination and support. Use comparable assumptions about transaction types and volumes. Do not assume the proposal with the lowest headline rate costs least overall.
Confirm the exact features and integrations required by your business. A payment professional can discuss processing and point-of-sale support; compatibility with your accounting, website or other tools must be demonstrated for the actual versions and workflow.
Have the accounting contact specify the reports and timing needed to connect sales, refunds, fees and deposits. Assign responsibility for investigating discrepancies and documenting corrections. Test real operating scenarios with suitable test data.
Use PCI Security Standards Council merchant guidance to frame questions about payment-data handling. Ask the processor and qualified technical provider which responsibilities remain with the business. A payment service is not a substitute for specialist cybersecurity work or proof of compliance.
Agree setup, access permissions, staff training and a cutover date that fits operations. Include the website or e-commerce provider where checkout changes are involved. Decide how existing orders, refunds and recurring arrangements will be handled.
Create a rollback or continuity plan with responsible contacts. Do not remove the old workflow before confirming the replacement and the obligations that remain under existing contracts.
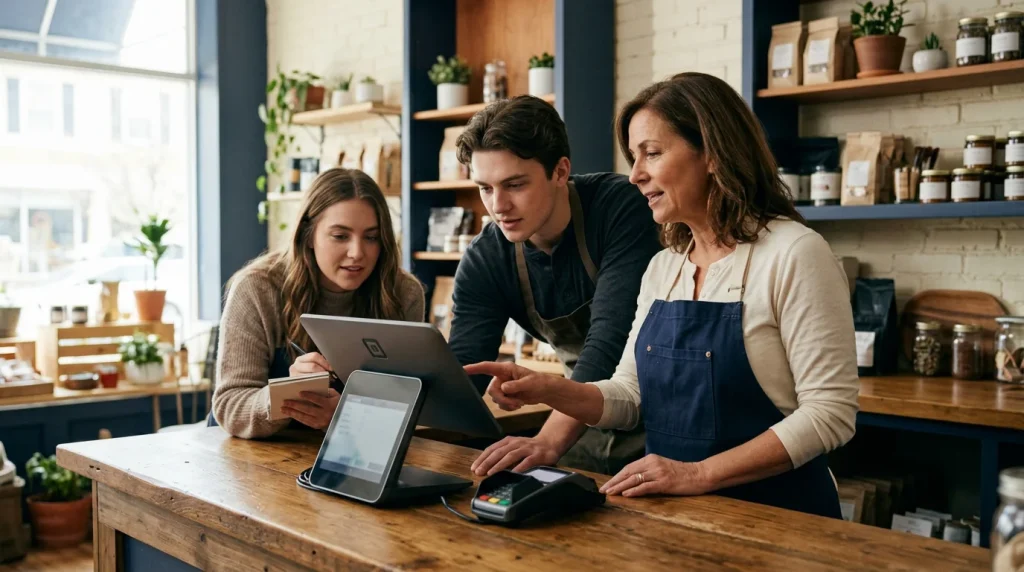
Check purchase, refund, decline, receipt and reporting scenarios before rollout, following provider-approved testing procedures. Train staff on their actual tasks and escalation routes. Explain any customer-facing changes clearly.
After launch, reconcile the first reporting cycles and record unresolved issues. Confirm who handles terminal faults, checkout failures, account questions and suspected incidents. Review whether the original operational problem is resolved without promising fee savings or increased sales.
Assign responsibilities in writing. Merchant processing, accounting, customer communication and technical security are different roles.
Start with the question you need answered. The current professional connections identify relevant roles, not a requirement to hire everyone. Confirm scope, qualifications, fees and availability directly. SJBA may not represent every profession you need.
SJBA editorial resource. Sources checked October 15, 2026. No member authorship or professional review is implied.
Move to the next step
Tell SJBA where you are in the process and which kinds of help you need.