Cash flow and reserves reviewed · As your scope requires
Financial professional
Financial Representative
Help organize household goals and cash-flow priorities.
SJBA Project Connections / Your Financial Life
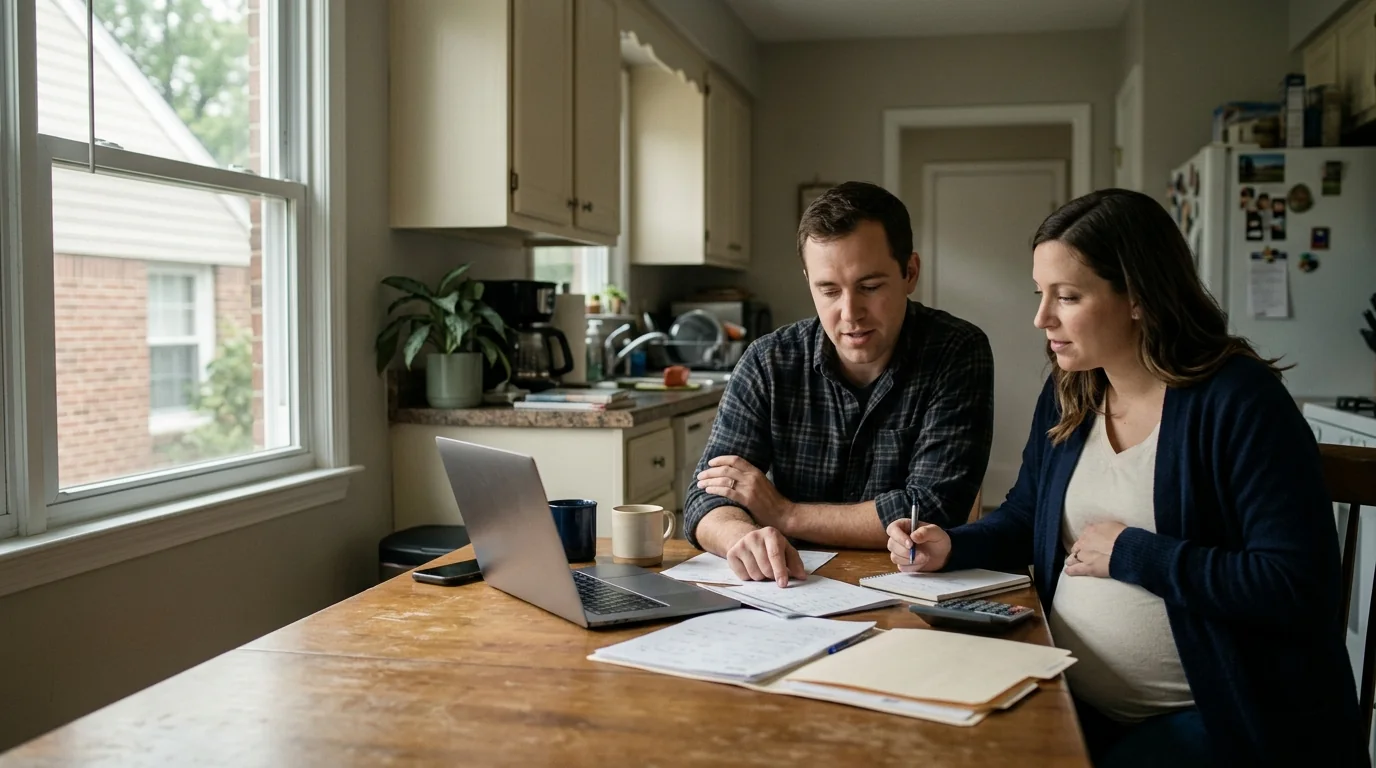
Preparing for a growing family connects everyday spending with work, insurance, housing and legal planning. You do not need to solve every future decision at once. Start with near-term cash flow and deadlines, then build a plan that can change as actual needs become clearer.
Your planning readiness check
Review the decisions below and mark the conversations you have prepared. Each item connects to the relevant part of this guide and the professional roles that may help. This is a planning aid, not a certification of readiness.
Your next step
Compare expected income with essential spending under more than one scenario. Ask an appropriate financial professional to help organize priorities if the choices compete. Consider how a delayed return to work or unexpected expense would affect the plan. Avoid treating available credit as the entire contingency strategy. Keep financial details in secure conversations with advisers rather than placing them in a general introduction request.
Read this part of the guideConfirm scope, qualifications, fees and availability directly.
Cash flow and reserves reviewed · As your scope requires
Financial Representative
Help organize household goals and cash-flow priorities.
Cash flow and reserves reviewed · As your scope requires
Accounting
Explain tax questions related to the household’s circumstances. Accounting scope: tax, records and financial management; obtain separate legal, valuation or investment advice where needed.

Your next step
Contact the benefits administrator and insurer about relevant enrollment, leave and coverage questions. Confirm deadlines and required documentation directly. Ask an insurance professional to explain options and limitations without assuming one product is appropriate for every family. Discuss healthcare decisions with qualified care providers. Keep a written record of confirmed information so the household is not relying on recollection during a busy transition.
Read this part of the guideConfirm scope, qualifications, fees and availability directly.
Benefits and coverage questions ready · As your scope requires
Life / Health / Medicare Insurance
Review relevant health and life coverage questions within scope.
Benefits and coverage questions ready · As your scope requires
Arrange this expertise independently when your scope requires it. Confirm relevant qualifications and experience before engaging a provider.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Benefits and coverage questions ready · As your scope requires
Arrange this expertise independently when your scope requires it. Confirm relevant qualifications and experience before engaging a provider.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Your next step
Ask an attorney about planning documents appropriate to the family’s circumstances, and an accountant about relevant tax questions. If a move is being considered, evaluate the full cost and timing rather than treating more space as an immediate requirement. Coordinate borrowing discussions with the actual income plan. Avoid making several large commitments simultaneously before understanding how they interact.
Read this part of the guideConfirm scope, qualifications, fees and availability directly.
Legal and housing decisions identified · As your scope requires
Arrange this expertise independently when your scope requires it. Confirm relevant qualifications and experience before engaging a provider.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Legal and housing decisions identified · As your scope requires
Mortgage
Evaluate borrowing questions if a housing change is being considered.

Legal and housing decisions identified · As your scope requires
Accounting
Explain tax questions related to the household’s circumstances. Accounting scope: tax, records and financial management; obtain separate legal, valuation or investment advice where needed.
Not every project needs every role. Current member availability is resolved live; unrepresented specialties are identified below.
Stage 01–05 · As your scope requires
Financial Representative
Help organize household goals and cash-flow priorities.
Stage 01–05 · As your scope requires
Life / Health / Medicare Insurance
Review relevant health and life coverage questions within scope.
Stage 01–05 · As your scope requires
Accounting
Explain tax questions related to the household’s circumstances. Accounting scope: tax, records and financial management; obtain separate legal, valuation or investment advice where needed.
Stage 01–05 · As your scope requires
Mortgage
Evaluate borrowing questions if a housing change is being considered.
Stage 01–05 · As your scope requires
Arrange this expertise independently when your scope requires it. Confirm relevant qualifications and experience before engaging a provider.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Stage 01–05 · As your scope requires
Arrange this expertise independently when your scope requires it. Confirm relevant qualifications and experience before engaging a provider.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Stage 01–05 · As your scope requires
Arrange this expertise independently when your scope requires it. Confirm relevant qualifications and experience before engaging a provider.
This expertise may be important for your project. This role is not an official SJBA category; consider arranging this service independently.
Preparing for a growing family connects everyday spending with work, insurance, housing and legal planning. You do not need to solve every future decision at once. Start with near-term cash flow and deadlines, then build a plan that can change as actual needs become clearer.
Discuss likely changes to income, leave, childcare, transport and household routines. Separate confirmed arrangements from estimates and identify which decisions have dates attached. Include one-time purchases and recurring costs without assuming every suggested product is necessary. Keep a small list of immediate priorities. Planning is easier when the household agrees what needs to be decided now and what can wait for more information.
Compare expected income with essential spending under more than one scenario. Ask an appropriate financial professional to help organize priorities if the choices compete. Consider how a delayed return to work or unexpected expense would affect the plan. Avoid treating available credit as the entire contingency strategy. Keep financial details in secure conversations with advisers rather than placing them in a general introduction request.
Contact the benefits administrator and insurer about relevant enrollment, leave and coverage questions. Confirm deadlines and required documentation directly. Ask an insurance professional to explain options and limitations without assuming one product is appropriate for every family. Discuss healthcare decisions with qualified care providers. Keep a written record of confirmed information so the household is not relying on recollection during a busy transition.
Ask an attorney about planning documents appropriate to the family’s circumstances, and an accountant about relevant tax questions. If a move is being considered, evaluate the full cost and timing rather than treating more space as an immediate requirement. Coordinate borrowing discussions with the actual income plan. Avoid making several large commitments simultaneously before understanding how they interact.
Compare estimates with actual spending and support needs. Update relevant records, contacts and professional advice after material changes. Decide when to review longer-term goals rather than trying to finalize them during every immediate decision. Keep responsibilities shared and explicit. A workable plan leaves room for changing circumstances while protecting essential needs and preserving informed choices.
Common problems include missing an enrollment deadline, budgeting only for purchases and overlooking income changes. Avoid individualized tax or insurance conclusions from a general guide. Confirm current requirements with the responsible administrator and use qualified advice for the decisions that depend on your circumstances.
Bring a short description of your situation, the decisions already made, your timing and any documents relevant to the questions above. Ask each professional to identify what they can handle, what needs another specialist, and which decision must come first. Agree the scope and fees before authorizing work.
Depending on your circumstances, your team may also need Estate-planning attorney, Employer benefits administrator, Qualified healthcare providers. These roles are included for planning completeness; an SJBA connection is not represented for them here.
Use these sources to check requirements relevant to your situation. Municipal approvals, provider scope and individual legal, tax or coverage decisions require direct verification.
Your planning workbook
Build a near-term cash baseline and compare changing work, care and household needs. Record verified dates and coordinate coverage, benefits and professional questions.
Download the Growing Family Financial Planner - PDF14 pages • Print-ready worksheets • PDF
Move to the next step
Tell SJBA where you are in the process and which kinds of help you need.